

Certified public accountants simplify complex finances in five main ways: they handle tax preparation and planning, build budgets and manage cash flow, explain the financial and tax impact of investment decisions, keep you compliant with tax and reporting rules, and find savings you would likely miss on your own. The common thread is that a CPA turns scattered numbers into a clear picture you can act on.
Finances become “complex” faster than most people expect. A side business, rental property, stock compensation, an inheritance, or income across two states can each add new forms, deadlines, and decisions. Working with a local firm, such as a Cherry Hill NJ CPA if you live in South Jersey, gives you someone who knows both federal rules and the state-specific requirements that apply to you. Here is how CPAs help across your financial matters, with practical examples.
What Makes Finances “Complex”?
Your finances are probably complex enough to benefit from a CPA if you have more than one type of income or a major financial event in the same year. Typical triggers include:
- Self-employment, freelance, or partnership income alongside a salary
- Rental properties or a recent home sale
- Equity compensation such as RSUs or stock options
- Investment accounts with frequent trades or crypto activity
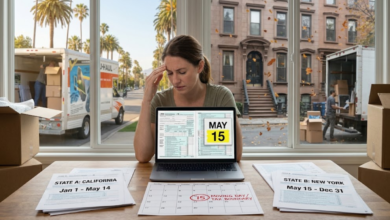
- Income earned in more than one state
- Major life changes: marriage, divorce, a new child, retirement, or an inheritance
- Owning a small business with employees, inventory, or sales tax obligations
Each of these adds rules that interact with each other, and that interaction is where mistakes and missed opportunities usually happen.
1. Tax Preparation and Year-Round Planning
Tax law changes regularly, and the details that matter for complex returns, such as depreciation on a rental, the qualified business income deduction, or the treatment of stock option exercises, are easy to get wrong. A CPA prepares accurate federal and state returns and documents the reasoning behind each position in case questions come up later.
The bigger value is planning. A CPA can help you time income and expenses, decide whether to make retirement contributions before the deadline, set up quarterly estimated tax payments if you have untaxed income, and choose a business structure that fits your situation. Planning happens before the year closes, which is why the most useful CPA relationships include at least one meeting in the fall.
**Example:** a salaried employee who starts consulting mid-year may have no tax withheld on consulting income. A CPA can calculate estimated payments for the rest of the year to reduce the chance of an underpayment penalty and a large bill in April.
2. Budgeting and Cash Flow Management
Complex finances often mean irregular income: commissions, seasonal business revenue, bonuses, or rent payments that arrive on different dates. A CPA helps you see when money comes in and goes out, so you can plan around the gaps instead of reacting to them.
The basic idea is simple. Compare monthly income with monthly expenses and look at the result:
| Monthly income | Monthly expenses | Result | Typical CPA response |
|---|---|---|---|
| $5,000 | $4,500 | $500 surplus | Direct surplus to emergency fund, tax reserve, or debt payoff |
| $5,000 | $5,200 | $200 deficit | Review spending categories, adjust timing, or plan for seasonal shortfalls |
The figures above are illustrative. In practice, a CPA builds a rolling forecast with your real numbers, separates personal and business spending, and sets aside money for taxes so a large bill never arrives as a surprise. For business owners, they may also review accounts receivable, payment terms, and inventory levels, which are the most common causes of cash crunches in small companies.
3. Clear Guidance on Investment Decisions
Investment choices have tax consequences that are easy to overlook. Selling a holding after more than a year generally qualifies for long-term capital gains treatment, while selling sooner usually means short-term rates. Traditional and Roth retirement accounts are taxed differently. Equity compensation can create a tax bill even when no cash changes hands.
A CPA explains how each option affects your tax bill and cash flow, helps you understand risk in plain terms, and coordinates with your financial adviser when you have one. Some CPAs also hold the Personal Financial Specialist (PFS) credential or are registered to give investment advice. If you want specific product recommendations, confirm the person is registered to provide them.
4. Staying Compliant With Tax and Reporting Rules
Compliance is where complexity becomes costly. Missed filings, late payroll tax deposits, unfiled state returns, and sales tax errors can all lead to penalties and interest. A CPA keeps track of deadlines, filing obligations, and recordkeeping requirements for both individuals and businesses.
For companies, compliance may include payroll filings, 1099 reporting for contractors, sales and use tax, and financial statements prepared to the standard lenders or investors expect. If you ever receive a notice or face an audit, a CPA can represent you before the IRS, which is one of the clearest advantages over unlicensed preparers.
Compliance checklist a CPA typically reviews
- Federal and state income tax returns filed and paid on time
- Estimated tax payments made each quarter where required
- Payroll taxes deposited and payroll returns filed
- Contractor payments reported on the correct forms
- Sales tax registered and remitted where your business has obligations
- Business records retained for the required period
5. Finding Savings and Opportunities
A CPA looks at your full financial picture, which makes it easier to spot savings that are invisible when you only look at one piece at a time. Common examples include:
- Deductions and credits you qualify for but have not claimed
- Retirement plans for the self-employed that reduce taxable income
- Recurring subscriptions or vendor costs that no longer make sense
- Better business entity or accounting method choices as income grows
- Health savings account and dependent care benefits that are underused
Savings will vary widely by situation, so be wary of anyone promising a specific refund or tax cut before reviewing your records.
How to Get the Most From a CPA
- **Keep records organized all year** in a shared folder or accounting software
- **Separate personal and business accounts** so expenses are easy to categorize
- **Tell your CPA about life changes** as they happen
- **Schedule a planning meeting before year-end**, not only a filing appointment
- **Verify the license** through your state board of accountancy before hiring
This article is general information, not personal tax or financial advice. Speak with a licensed CPA about your own circumstances.
Bottom Line
Complex finances do not have to feel overwhelming. A certified public accountant brings order to taxes, cash flow, investments, and compliance, and often finds savings along the way. If you have multiple income streams or a major financial event this year, start the conversation early. For more, read about the role of a certified public accountant in your financial success and how CPAs offer peace of mind to busy professionals. Founders setting growth targets may also like 5 ways startups can benefit from OKRs, and you can find more guides in our finance category.
Frequently Asked Questions
What does a CPA do for complex finances?
A CPA prepares and plans your taxes, builds budgets and cash flow forecasts, explains the tax impact of investment choices, keeps you compliant with filing rules, and looks for savings. They bring all the pieces of your finances into one clear view.
When should I hire a CPA instead of using tax software?
Consider a CPA when you have self-employment income, rental property, equity compensation, income in several states, or a major life event. Software works well for simple returns but cannot advise you on planning decisions.
Can a CPA give investment advice?
A CPA can explain the tax side of investment decisions. Specific investment recommendations require additional registration, so confirm the person is registered as an investment adviser or holds a relevant credential if you want product advice.
How do CPAs help small businesses with cash flow?
They forecast income and expenses, review payment terms and receivables, set aside money for taxes, and flag upcoming shortfalls. This helps owners make hiring and spending decisions with fewer surprises.
How do I know if a CPA is licensed?
Search your state board of accountancy’s license lookup or the national CPAverify database. Both show whether the license is active.